GAF Certified Contractor BBB A+ 4.9 stars on Google (62 reviews)

Free roof inspections Written prices, no surprises Financing available

XPRO Claim-to-Completion™ · Insurance claims

Insurance claim restoration without the guesswork.

We make the scope buildable before we build the home.

For a covered replacement-cost insurance claim, your deductible is typically the homeowner portion for the covered like-kind-and-quality restoration. XPRO ELITE reviews the carrier’s construction estimate, identifies missing or incomplete construction components, documents necessary supplements, and works to resolve material scope gaps before non-emergency production begins.

Your deductible. A documented scope. A buildable restoration.

4.9 stars · 62 Google reviews · BBB A+ · GAF Certified

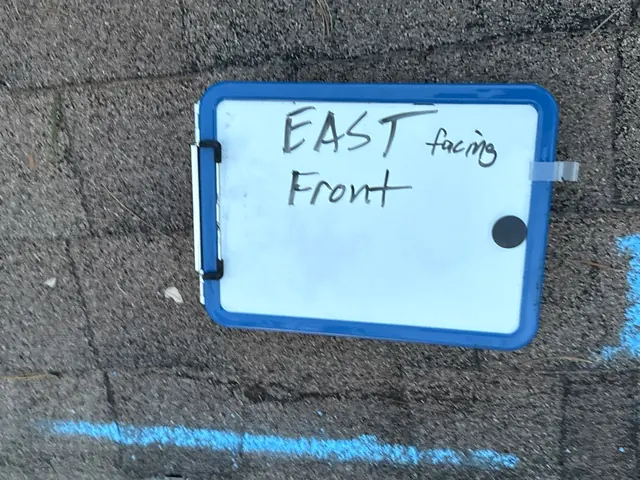
Whiteboard labeling the east-facing front slope beside chalk-marked damage during a Milford, Ohio inspection
Milford, OHSlope labeled · damage documented

Already have an insurance estimate?

Send it to XPRO ELITE. We will compare the written construction scope with what the property actually requires and show you what is approved, what may be missing, and what needs to be clarified before the build.

The first insurance estimate is a starting point, not always the final construction plan

Insurance estimates are often written before every construction detail is known. That estimate may already be complete. But when it is not, the answer should not be to cut corners, guess, or automatically charge the homeowner for every missing component.

XPRO reviews the scope for the actual work required to perform the restoration. When a necessary construction item is not adequately reflected in the current carrier estimate, XPRO prepares the documentation needed for the carrier to review it.

Plain English

What is a supplement?

A supplement is the insurance-restoration industry’s term for additional construction documentation submitted after the original estimate, when the contractor identifies legitimate scope, quantity, material, pricing or construction requirements that were not adequately included.

  1. Carrier estimate“Here is the construction scope we currently have.”
  2. XPRO review“Here is what the project actually requires to be properly executed.”
  3. Supplement“Here is the documented difference, why it is needed, and the evidence supporting it.”
  4. Carrier reviewThe carrier reviews the submitted construction information and determines what it will add, modify, request more information about, or decline.

What the documentation can include

  • Xactimate line items and quantities
  • Roof and exterior measurements
  • Photos and videos
  • Material invoices or market pricing
  • Manufacturer installation requirements
  • Building-code requirements
  • Product availability or discontinuation
  • Repairability evidence
  • Sequencing, safety and access needs
  • Concealed or newly discovered conditions
  • Written construction rationale

Every item starts with a construction question: what work is required, why is it required, what evidence supports it, and why can the currently written scope not be properly executed without it?

Why XPRO supplements before we build

Because once the roof or exterior is under construction, the homeowner should not be discovering that major required components were never resolved.

For non-emergency reconstruction, XPRO works to address material known scope differences before production. That gives everyone a clearer blueprint.

Before we schedule production

The XPRO Buildable Scope Standard™

Before we schedule production, we work to establish five things.

  1. What is approved

    The current carrier-approved construction scope.

  2. What is missing

    Necessary components, quantities or work not adequately included.

  3. What is supported

    Photos, measurements, estimating data, code and manufacturer information, product data, repairability evidence and other relevant construction documentation.

  4. What is pending

    Items that still require carrier review or additional information.

  5. What you actually owe

    Your deductible plus any clearly disclosed non-covered work or upgrades you personally choose.

No mystery balance.

Before production, we want you to understand the approved scope, the deductible, what is still pending, and any known homeowner-paid items.

The No-Surprise Scope Commitment

XPRO does not intentionally build from a known materially deficient scope and then surprise the homeowner with the shortfall afterward.

If a concealed condition shows up after tear-off, we document it immediately and, where appropriate, submit the construction basis for carrier consideration before treating it as a homeowner-paid change whenever reasonably possible.

Your deductible

Your deductible, explained clearly

For many covered replacement-cost claims, the deductible is the primary homeowner contribution toward the covered like-kind-and-quality restoration. That does not mean every insurance claim is automatically “deductible only.”

XPRO will show you the construction numbers we have. Your carrier or licensed insurance professional controls coverage and policy interpretation.

Can’t pay the deductible all at once? Ask about available payment or financing options. The deductible remains your responsibility, but an approved payment structure may let you move forward without turning a required restoration into an immediate cash crisis.

What happens when insurance sends more than one check?

Many replacement-cost claims are paid in stages. A common structure looks like this.

  1. Estimate

    The carrier establishes a replacement-cost estimate.

  2. Deductible

    The deductible is applied.

  3. First payment

    An initial actual-cash-value payment is issued.

  4. Depreciation held

    Recoverable depreciation may be withheld.

  5. Work completed

    The contractor completes the qualifying work.

  6. Paperwork

    Final invoices and completion documentation are submitted.

  7. Final release

    The carrier may release recoverable depreciation according to the policy and claim.

If a mortgage company is listed on the property, it may also be named on a claim check and have its own endorsement or draw process. XPRO helps organize the construction documentation needed for claim completion. The carrier and mortgage company control their own payment procedures.

What if we find additional damage during tear-off?

Some conditions cannot be confirmed until materials are removed. If XPRO discovers a legitimate concealed construction condition:

  1. We document it

    The newly visible condition is documented as soon as it is exposed.

  2. We explain it

    What is required, and why.

  3. We submit it

    Where appropriate, the supplemental construction information goes to the carrier for review.

  4. We tell you first

    Any unresolved homeowner responsibility is communicated before we proceed with discretionary additional work.

The goal is not to surprise you. The goal is to solve the construction problem with documentation.

If the carrier disagrees

What if the carrier says no?

A supplement is not an automatic approval. If the carrier disagrees with an item, XPRO can respond with additional construction evidence when available: measurements, photographs, installation requirements, product information, repairability documentation, code support, or a clearer explanation of how the proposed work must actually be performed.

If a coverage decision remains unresolved, the homeowner and carrier control that coverage issue. XPRO does not act as a public adjuster and does not make policy coverage determinations.

What XPRO can do is make the construction issue unmistakably clear. Can the approved scope actually be built? What does the work require? What evidence proves it?

Stop choosing between “cut corners” and “pay thousands more”

An incomplete first estimate should not automatically force the homeowner into two bad choices.

Bad choice A

Build less than the project actually requires

Bad choice B

Personally pay for every missing construction component

The third path

Document it. Submit it. Then build.

Document the construction requirement and submit it for carrier review before the project is built. That is what XPRO’s supplement process is designed to do.

One team from inspection through completion

XPRO can coordinate the construction side of the claim from start to finish, so you are not stuck acting as the middleman between your contractor and your carrier.

With your authorization, we can communicate with your adjuster about the construction scope, estimates, measurements, invoices, photos, supplements and scheduling.

Field photos · our jobs

What documentation looks like on our jobs

Proof, not promises

Recent insurance claims field notes

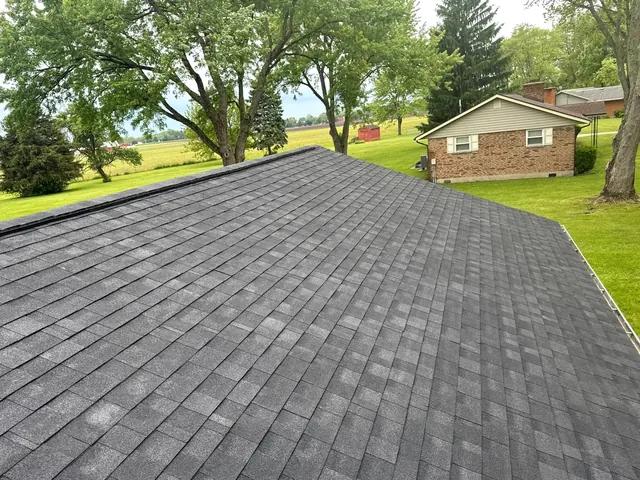
Finished XPRO ELITE shingle roof on a ranch home in Jamestown, Ohio
Jamestown, OHRoof replacement

Jamestown, OH · May 2025

Eight days after 3-inch hail, on the roof.

  • Inspected April 12, 2025, eight days after NOAA logged 3-inch hail at Jamestown
  • Tear-off May 19 with tarps protecting the lawn
  • Damaged decking marked and replaced
  • New roof finished May 20
  • Chimney flashing checked at the May 27 final

Every step is in the dated job log: inspection, tear-off, decking, final.
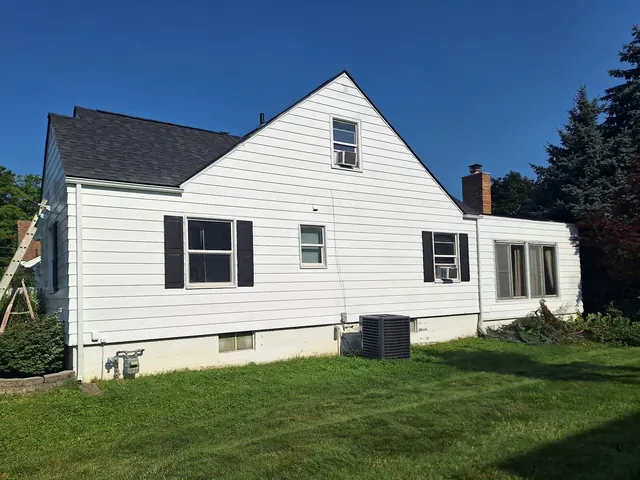
Finished XPRO ELITE roof replacement on a cape cod home in Piqua, Ohio
Piqua, OHRoof replacement

Piqua, OH · July 2025

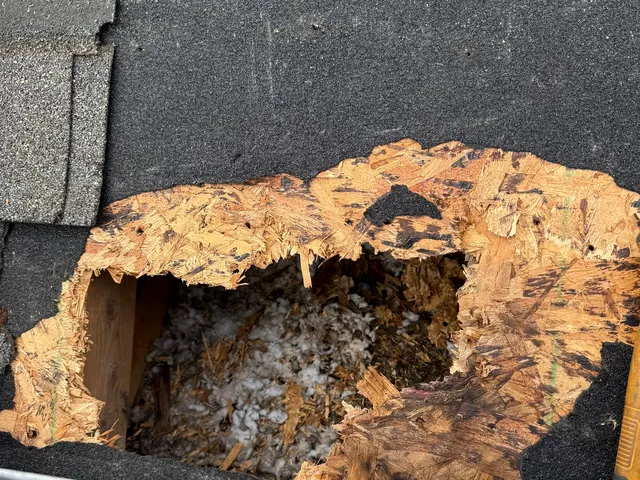
Tarps, a collapsed ceiling, then a whole new roof.

  • Low-slope roof inspected under tarps, December 27, 2024
  • Moisture-meter readings, January 2025
  • Interior ceiling collapse documented April 17, 2025
  • Tear-off April 28 exposed rotted decking
  • Finished new roof photographed July 3, 2025

Six months of dated photos, from the first tarp to the final.

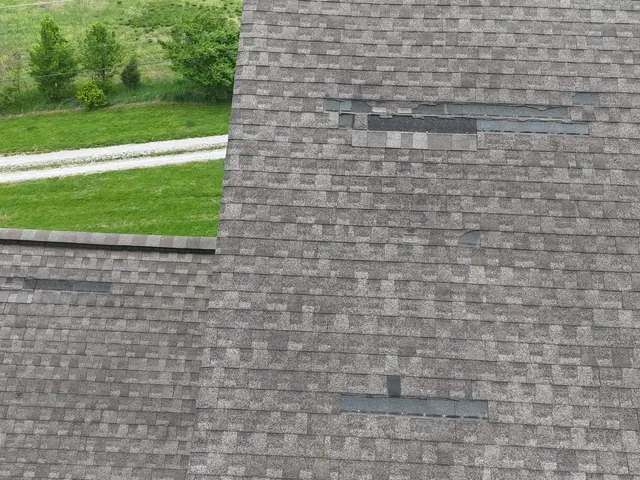
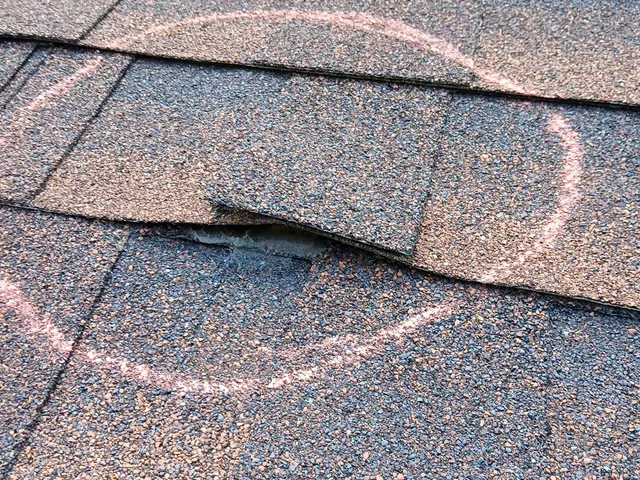
Drone close-up of displaced shingles found during a storm inspection in Hamilton, Ohio
Hamilton, OHStorm inspection + claim documentation

Hamilton, OH · April–November 2025

Building the file on a Hamilton storm roof.

  • Storm inspection with chalk-marked hits, April 2025
  • Shingle repairability test, June 2025
  • Existing shingle measured, July 2025
  • GAF QuickMeasure roof report
  • Interior ceiling stain documented, November 2025

Not every job starts with a hammer. This one started with evidence.

Ryan Sheehan, owner of XPRO ELITE Exterior Builders, standing beside his XPRO ELITE truck
Owner Ryan Sheehan · XPRO ELITE Exterior Builders

The name on the truck is the name on the job

Meet Ryan Sheehan. You’ll deal with the owner.

Ryan has spent 20 years in the roofing and exterior trades and the last 3 building XPRO ELITE into one of the Miami Valley’s top-rated names — 4.9 stars across 62 Google reviews and an A+ with the BBB.

“If you need a roof, call 937-80-ROOFS.”

— Ryan Sheehan, Owner
20years in the industry
3years as XPRO ELITE
GAFCertified Contractor

Google reviews

What homeowners say

4.962 reviews on Google (opens in a new tab)
  • “Dominic was there every step of the way to help navigate the complicated insurance claim process, and went above and beyond to assist us in proving an entire replacement was necessary. Once the day came to make the replacement, the crew was fast and efficient. The replacement was completed in 2 days and once finished the only sign they had even been there was our brand new roof.”

    Tatum S. · Google review · Roof repair for storm & wind damage · Read on Google (opens in a new tab)

  • “…70 mile an hour winds that rip 15 shingles off my roof, Dominic was right here the next day to have his crew patch up my damaged roof. It took three different submissions by XPro Elite to finally get a full roof replacement approved by Allstate. I would say just be patient. Trust the process. These guys know what they’re doing. Also, if you need a loan to replace your roof, they have great options. Ryan was all over it.”

    Kevin H. · Google review · Roof repair for storm & wind damage · Read on Google (opens in a new tab)

  • “Did an amazing job on my roof. Excellent when dealing with insurance. Showed up and knocked it out in one day. Highly recommend them to anyone.”

    Thomas U. · Google review · Roof repair for storm & wind damage · Read on Google (opens in a new tab)

FAQ

Insurance Claims questions

Do I really only pay my deductible?

For a covered replacement-cost claim where XPRO is completing the carrier-approved like-kind-and-quality restoration scope, the deductible is typically the homeowner contribution we plan around. However, ACV-only settlement, non-recoverable depreciation, policy limits, exclusions, unresolved items, upgrades, or unrelated work can create additional homeowner responsibility. XPRO will identify known construction differences before production whenever possible.

Will XPRO waive or “eat” my deductible?

No. XPRO’s offer is not based on hiding or rebating the deductible. The deductible remains the homeowner’s responsibility. If affordability is the problem, ask about available payment or financing options.

What exactly is a supplement?

A supplement is additional construction documentation submitted to the insurance carrier when the current estimate does not adequately include required scope, quantities, materials, pricing, or other legitimate construction needs. It may include an updated estimate, photos, measurements, invoices, code or manufacturer support, material information, or repairability documentation.

Does a supplement mean XPRO is just trying to increase the price?

No. A proper supplement starts with a construction question: what must actually be done to complete the restoration? The supporting amount follows the required work. XPRO documents the item and why it is necessary; the carrier reviews that information.

Why not just build whatever is on the first insurance estimate?

If the first estimate is complete and executable, there may be little or nothing to supplement. If it is missing known required work, building first can create avoidable uncertainty. XPRO’s process is to identify and address material construction gaps before non-emergency production whenever possible.

Does the insurance company have to approve every supplement?

No. The carrier reviews each submitted item and may approve it, modify it, request additional information, or decline it. XPRO’s role is to provide accurate construction documentation, not to guarantee a coverage decision.

What if the carrier approves some supplement items but not others?

XPRO separates the items into approved, pending, and unresolved categories. When additional evidence exists, we can provide it. Before production, we want the homeowner to understand any known unresolved amount that could affect the project.

What if something is discovered only after tear-off?

We document the newly visible condition and determine whether it relates to the contracted restoration. When appropriate, we prepare supplemental construction documentation for carrier review. We do not treat a genuinely concealed condition as a planned upsell.

What is ACV?

ACV means Actual Cash Value. In simple terms, it generally reflects a depreciated value rather than the full current replacement cost. The exact settlement method depends on the policy and carrier.

What is RCV?

RCV means Replacement Cost Value. A replacement-cost claim may still be paid in stages, with depreciation held until qualifying work is completed and documented. The carrier determines the payment terms under the policy.

What is recoverable depreciation?

It is an amount the carrier may withhold from the initial payment and later release after the covered replacement work is completed and properly documented, subject to the policy and claim.

Why did I receive less money than the total shown on the estimate?

Common reasons include the deductible, depreciation, staged payments, prior payments, or policy-specific settlement terms. XPRO can explain the construction figures on the estimate, while coverage and payment interpretation remain with the carrier or your licensed insurance professional.

Does a supplement create a second deductible?

A supplement changes or clarifies the claim’s construction estimate; it is not a separate project by itself. Your carrier and policy control how the deductible applies to the claim.

What if my mortgage company is on the insurance check?

The lender may require endorsement, inspection, or a draw process before funds are released. That is normal on many insured properties. XPRO can provide the construction documents the lender or carrier requests, but the mortgage company controls its own process.

Can I upgrade my roof or siding?

Yes. If you choose materials or work beyond the covered like-kind-and-quality restoration, XPRO will separate the upgrade from the insurance scope so you can see the customer-paid difference.

What if insurance only approved a repair instead of replacement?

XPRO evaluates whether the proposed repair is actually executable from a construction standpoint. Repairability, product availability, installation requirements, surrounding material condition, and other relevant facts can be documented for carrier review. The carrier makes the coverage decision.

Can XPRO talk directly to my adjuster?

With the proper customer authorization, XPRO can communicate about the construction scope, estimates, measurements, invoices, photos, supplements, scheduling, and other contractor-related issues.

Does XPRO interpret my insurance policy?

No. XPRO is the contractor. We explain construction requirements and the cost to perform the work. Policy coverage questions should be answered by your carrier, agent, attorney, or other appropriately licensed professional.

Can XPRO guarantee my insurance company will approve the claim or supplement?

No contractor can honestly guarantee a carrier’s coverage decision. XPRO can guarantee that our construction position will be documented, organized, and supported with the evidence reasonably available to us.

Will filing a claim raise my premium?

XPRO cannot predict how an insurer will underwrite or price your policy. Ask your insurance agent or carrier about claim-history and premium questions.

Why does XPRO need my carrier estimate?

Because the estimate tells us what the carrier currently understands the project to include. We compare that written scope to the actual construction requirements so we can identify differences before production.

What is the biggest advantage of XPRO’s process?

Clarity before construction. We want the homeowner, contractor, and carrier to have the most complete construction picture possible before the project is built, instead of discovering known scope gaps after the fact.

Do I have to use the contractor my insurer recommends?

No. You can choose your own contractor.

XPRO Claim-to-Completion™

You already pay for insurance. Make sure the construction scope is actually complete.

The goal is not to inflate a claim. The goal is not to turn every job into a fight. The goal is simple:

  1. Identify the covered damage.
  2. Understand the carrier’s current scope.
  3. Document what the restoration actually requires.
  4. Resolve material construction gaps.
  5. Build the approved work correctly.
  6. Close the construction file cleanly.

That is XPRO Claim-to-Completion™.

XPRO Claim-to-Completion™

Your deductible. A documented scope. A buildable restoration.

You’re not committing to a roof replacement by sending us your estimate. You’re asking XPRO to review the construction scope and explain what is currently approved, what may be incomplete, and what the next construction step should be.

  • Free storm-damage inspection
  • Your carrier estimate compared with what the build requires
  • Approved, pending and missing items shown in writing
  • Your deductible and any known homeowner-paid items, before production
Prefer to talk now? 937-80-ROOFS (937) 807-6637

Start my XPRO claim review

Free · No commitment to build · About a minute

  1. 1Project
  2. 2Claim
  3. 3Property
  4. 4Contact
What can we help with?

By submitting, you agree XPRO ELITE may contact you by call, text or email about your project. No spam, no sharing. See our privacy policy.

Find out what your roof really needs.

Free X-Ray Roof Inspection with photos. No pressure, no obligation.

Call nowInstant quoteFree inspection
Get Instant Quote